For UK property investors, two strategies have come to dominate the conversation: traditional buy-to-let (BTL) and houses in multiple occupation (HMOs). Whilst buy-to-let investment has been top-of-mind for many decades, HMO investing seems to have leapt to prominence over the last few years.
Both can generate strong rental returns, but they appeal to very different types of tenants, require different levels of management, and work best in different locations. Understanding these differences is crucial before committing to either model.
Below, we’ll explore what each investment type looks like in practice, who the typical tenants are, and what kinds of towns and cities suit them best. We’ll also weigh up the pros and cons to help you decide which strategy might be right for your portfolio.
What Is a Traditional Buy-to-Let
A standard buy-to-let property is one that’s rented to a single household — usually a family, couple, or professional tenant. It’s the most familiar and widely used investment model, in part because it’s straightforward to manage and finance.
Over the years, North Property Group has sold hundreds of buy-to-let apartments to investors who have seen great returns, both in terms of rental yields and capital appreciation.
For many landlords, buy-to-let forms the foundation of their portfolio because it balances consistent income with long-term capital growth potential.
Typical tenants include:
- Young professionals renting before buying their first home
- Families seeking stability in the rental market
- Retirees or downsizers looking for smaller, manageable properties
With properties ranging from a new-build two-bedroom flat in a city centre to three-bedroom terraced houses in a commuter town, the housing stock will be familiar to many.
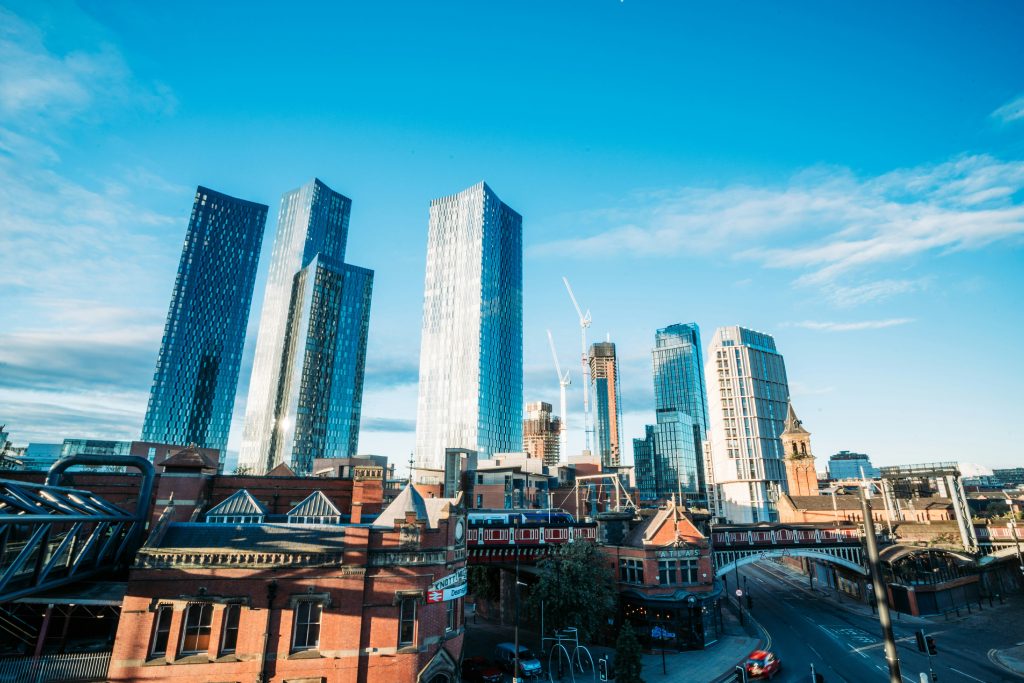
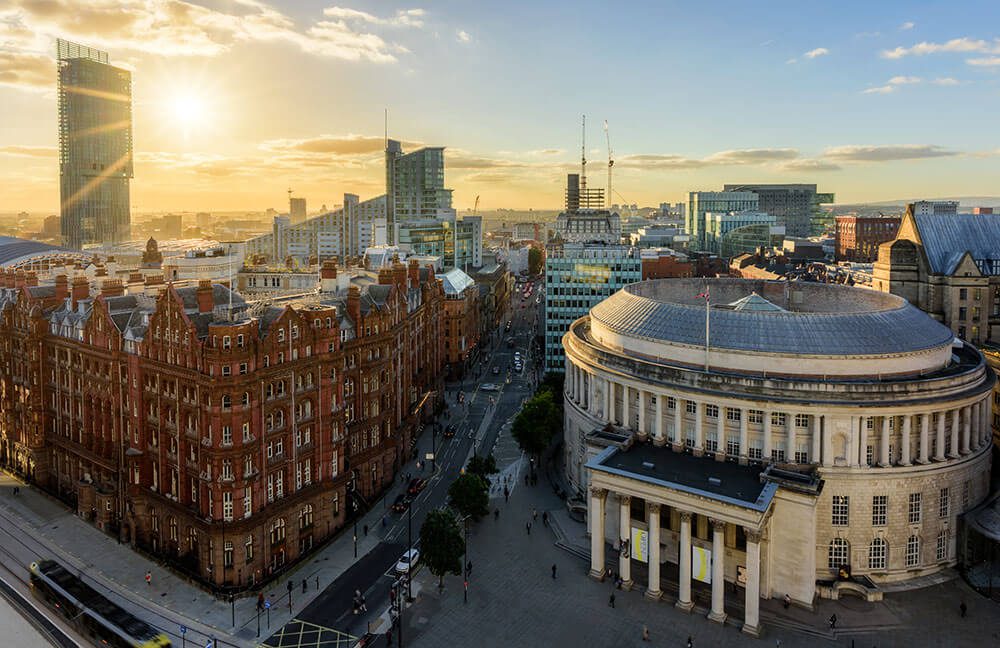
Buy-to-let works well in major cities such as Manchester, Birmingham, and Leeds with strong job markets. It’s also successful in commuter towns like Reading, Ashford, and Milton Keynes with demand from London workers. Landlords will even find success in university towns such as York or Exeter, where overseas students and their parents may invest in suitable accommodation.
What Is an HMO?
An HMO (House in Multiple Occupation) is a property where three or more unrelated tenants live together and share communal facilities such as kitchens or bathrooms.
This investment model is more complex, with a much higher barrier to entry as well as strict regulatory considerations, but it can deliver higher headline yields.
HMOs are popular in areas with strong student populations, migrant workers or temporary employees. In some cases, they can be used by local authorities and charities to house vulnerable tenants. As such, they require more hands-on management and a sharper focus on compliance with regulations.
Typical tenants include:
- University students looking for affordable shared accommodation
- Seasonal or contract workers who prefer short-term room rentals
- Niche tenant groups who need temporary shelter
Typical HMOs tend to be conversions, depending on the local housing stock. It’s not uncommon to see a large Victorian terrace converted into multiple bedrooms or a suburban property retrofitted for shared living.
HMOs are often found in student cities like Nottingham, Sheffield, or Liverpool. Affordable towns like Stoke-on-Trent or Sunderland where shared housing meets demand for low-cost rentals are popular locations.
The Strengths of Traditional Buy-to-Let
Buy-to-let’s strength lies in its simplicity and stability. It’s an investment model that lenders, landlords, and tenants all understand well.
Because properties are let to a single household, the management burden is lower, and the risk of sudden tenant turnover is reduced.
For landlords, this often translates into fewer headaches and steadier returns.
Key benefits include:
- Predictable income – Longer tenancies mean more reliable rental flows
- Mortgage flexibility – Easier access to finance with a wider choice of products
- Wider tenant demand – Families and professionals provide consistent markets
- Easier resale – Properties can be sold to both landlords and homebuyers
- Location flexibility – Works in most UK towns and cities
The Risks of HMO Investment
HMO investment can be attractive on paper because of its potential for higher rental yields.
However, those returns often come at the cost of higher risk and more complex management.
HMOs require careful location selection, significant upfront investment to meet licensing requirements, and ongoing costs that can quickly erode profits. For this reason, they’re often better suited to more experienced landlords.
Many lenders won’t provide mortgages for HMOs due to the associated risks, which means most of the opportunities available are cash only purchases.
Key challenges include:
- Strict regulations – Licensing and compliance requirements are costly and time-consuming
- Higher running costs – Furnishings, utility bills, and repairs all add up
- Greater turnover – Student and professional tenants tend to move more often
- Financing difficulties – Mortgages are harder to secure and usually more expensive
- Location dependency – Not every town or city has the right demand for HMOs
Buy-to-Let vs HMOs: Which Is Best?
Both models can be profitable, but they appeal to different investor profiles.
HMOs may suit those who are comfortable with intensive management and want to chase higher gross yields in niche markets.
In contrast, buy-to-let remains the safer and more flexible choice for most landlords, offering consistent demand, easier access to finance, and better long-term resale prospects.
Ultimately, the decision comes down to your risk appetite, investment goals, and level of involvement. We’d always recommend caution and diligent research before moving ahead with any investment, but this is particularly true of HMO investment.
If you’re aiming for stability and growth, buy-to-let provides a proven route, which is why North Property Group has built its success on offering these properties to our clients.
Ready to explore buy-to-let opportunities tailored to your goals? Our team can help you identify the right properties, in the right towns, for long-term success.
Book a free strategy meeting today.