Last updated: September 2026
Property investment means buying real estate — a flat, house, or commercial unit — with the goal of generating a financial return, either through rental income, an increase in the property’s value over time (capital growth), or both. It’s one of the most established forms of investing in the UK, and today around 1 in 5 UK households live in a privately rented property, with roughly 4.7 million buy-to-let homes now let across the country.
Unlike a pension or stocks and shares ISA, property investment gives you a physical, tangible asset — but it also comes with running costs, management decisions and risks that don’t apply to most other asset classes. This guide covers how it actually works, the different ways to do it, what returns and risks look like in 2026, and how to get started.
How does property investment make money?
Property investors make money in two ways, and most strategies lean on one more than the other:
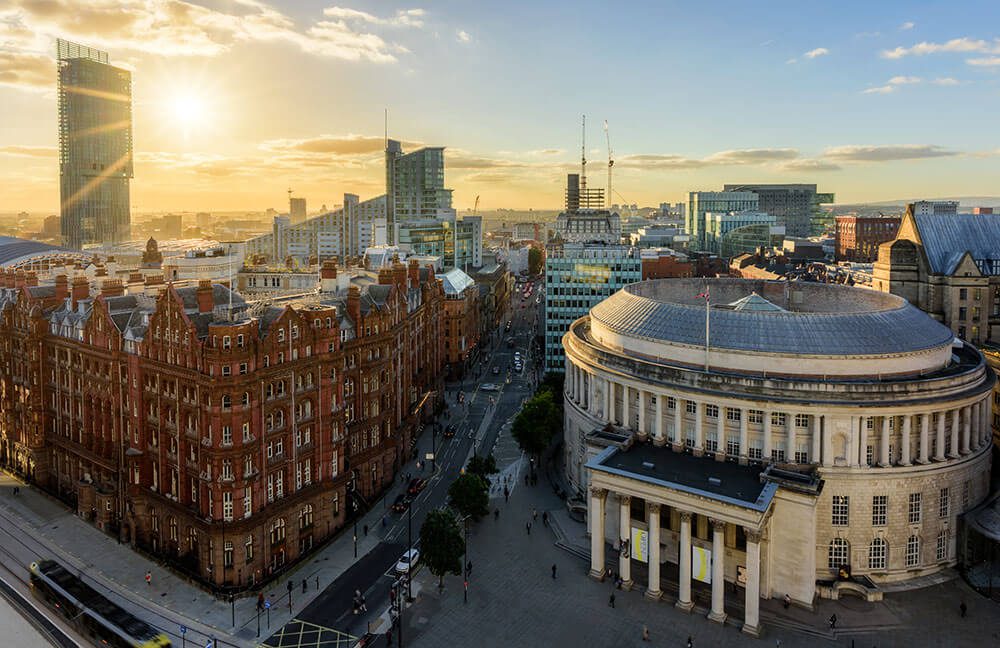
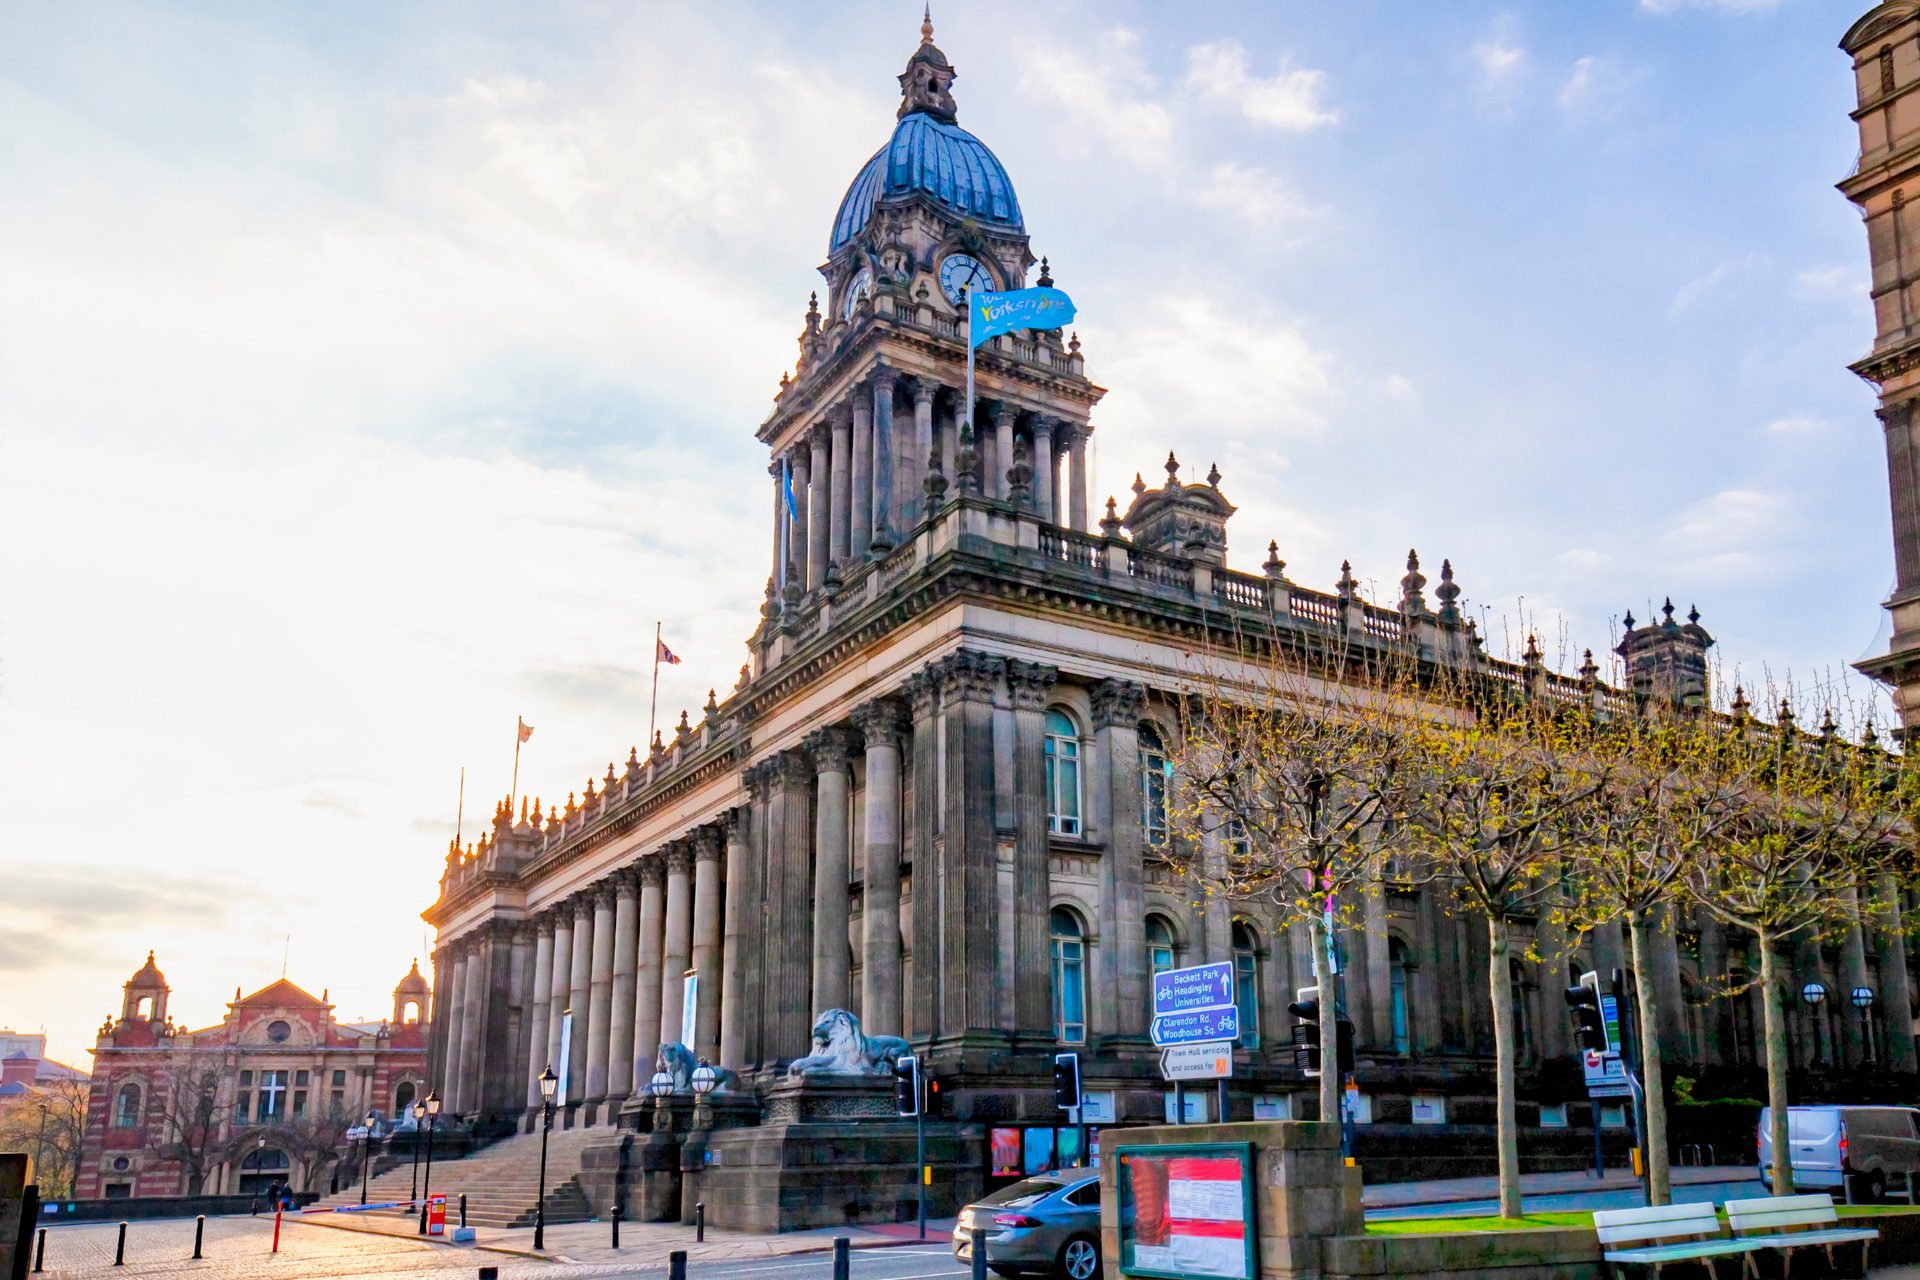
- Rental yield is the income a property generates, expressed as a percentage of what you paid for it. Gross yield is calculated as annual rental income ÷ purchase price × 100. The UK average gross rental yield reached 7.15% in Q3 2025, though this varies significantly by city and property type — city-centre flats in Manchester, Leeds and Liverpool regularly outperform the national average, often reaching 6–9%+, while much of London and the South East sits closer to 3–4%.
- Capital growth is the increase in a property’s value over time, realised when you sell. This is driven by local demand, regeneration, infrastructure investment and the wider housing market — and it’s the harder of the two to predict, since it depends on conditions years into the future rather than today’s rent roll.
Most investors weigh both when choosing where and what to buy: a high-yield property in a slower-growth area suits someone prioritising income now, while a lower-yield property in a regeneration hotspot suits someone playing a longer game on capital growth.
What are the different types of property investment?
Property investment isn’t one strategy — it covers several distinct approaches, each with a different risk, effort and return profile:
- Buy-to-let is the most familiar route: buying a residential property to let out to tenants, either a single unit or a portfolio built up over time.
- Off-plan and new-build investment means buying a property before or during construction, typically at a price below the projected completion value, with the potential for capital growth over the build period. This is a large part of what we do at North Property Group — see our [dedicated guide to off-plan investment] for the specifics.
- Build-to-rent (BTR) developments are purpose-built rental schemes, often professionally managed at scale, that individual investors can buy units within.
- Commercial property — offices, retail units, industrial space — behaves differently from residential: typically longer leases and higher yields, but higher entry costs and different risk factors. [See our commercial vs residential comparison] for more detail.
- Buy-to-sell / flipping involves buying a property below market value, often renovating it, and selling on for a profit rather than holding it as a rental asset.
- Portfolios combine several of the above — many experienced investors deliberately mix property types and locations to balance yield, growth and risk rather than relying on a single asset.
Is property investment still worth it in 2026?
For the right property in the right location, most independent analysis still frames property as a reasonable way to diversify a portfolio — but the calculation looks different than it did five or ten years ago, and it’s worth being specific about why.
The Bank of England base rate has held at 3.75% through mid-2026, which has stabilised — though not eliminated — mortgage cost uncertainty for leveraged investors. The stamp duty surcharge on second homes and buy-to-let purchases remains at 5% on top of standard rates, so upfront costs need to be built into any return calculation from day one, not treated as an afterthought.
Against that, the structural picture hasn’t changed: the UK continues to build fewer homes than household formation requires, particularly in city centres with strong graduate retention and inward migration. Average gross yields nationally are still comfortably ahead of most other passive income asset classes, and cities like Manchester, Leeds and Liverpool continue to outperform the national average on both yield and forecast growth.
The honest answer is that “is property a good investment” isn’t really a yes/no question — it depends on the specific property, price, location and your own financial position. It’s a reasonable option for many investors, provided the numbers are based on realistic assumptions rather than marketing headlines.
What are the risks of property investment?
Any honest guide to property investment has to cover the downside, not just the upside:
- Void periods — time between tenancies when a property earns no rent but still costs money (mortgage, service charge, insurance) — are the most common way projected yields fail to materialise in practice.
- Market risk — property values can fall as well as rise, and capital growth forecasts are exactly that: forecasts, not guarantees.
- Leverage risk — if you’re using a mortgage, a fall in property value or rental income affects your equity and cash flow more severely than it would an unleveraged investor, and rate changes at remortgage can significantly change your monthly costs.
- Liquidity risk — unlike shares, you can’t sell a fraction of a property or exit within days; selling a property typically takes weeks to months.
- Unexpected costs — repairs, compliance requirements (EPC ratings, safety certificates) and void-period costs all eat into returns if you haven’t budgeted a reserve for them.
None of these are reasons to avoid property investment — they’re reasons to go in with realistic numbers, a financial buffer, and (for most people) professional guidance rather than assumptions borrowed from a developer’s brochure.
How much money do you need to start?
This varies by strategy and property, but as a general guide: mortgaged buy-to-let and off-plan purchases typically require a deposit of 20–40% of the purchase price (25% is the most common starting point), plus the 5% stamp duty surcharge, legal fees, and — for off-plan purchases — staged payments through to completion.
On top of the purchase price, budget for ongoing costs: mortgage payments if applicable, letting agent or management fees, service charges (for flats), insurance, and a maintenance reserve. A common mistake is budgeting only for the deposit and missing the layer of costs that sit on top of it.
Property investment carries risk — values and rental income can rise as well as fall, and forecasts aren’t a guarantee of future performance. This article is general information, not personalised financial advice; speak to our team or an independent financial adviser about your own circumstances.
Fully managed, tenant-find, or self-managed: how hands-on do you want to be?
Property investment doesn’t have to mean becoming a hands-on landlord. Most investors choose from three levels of involvement:
- Fully managed — a letting agent or management company handles everything from finding tenants through to end-of-tenancy checkout, repairs, rent collection and compliance. This suits investors who want rental income without day-to-day involvement, including many overseas or out-of-area investors.
- Tenant-find only — an agent sources and vets the tenant, then the investor manages the tenancy directly.
- Self-managed — the investor handles everything themselves, from marketing the property to handling maintenance requests. This maximises the share of rental income you keep, but requires the most time and hands-on knowledge.
Find out more
If you’d like to learn more about property investments, get in touch with the friendly team at North Property Group for more information and expert advice.